Workers’ Comp for Contractors · 949.305.5577
Free X-Mod Review · California Contractors
Most contractors have never had anyone actually review their Experience Modification Rate. Errors are common. Open reserves are common. Wrong class codes are common. You just never knew because nobody looked.
☎ Call us at 949.305.5577Get My Free X-Mod Review →
We look. Free. No obligation. No pitch.
Contractor specialist since 2007 · CA licensed #0F56527 · Advisor-first, not a sales pitch
The Problem
Most contractors know a high mod means higher premium. Fewer know it can disqualify them from jobs entirely.
General contractors, public agencies, and project owners increasingly screen subcontractors by EMR before they ever look at a price. If your mod is over 1.0 — or even over 0.85 on certain projects — you don’t get to bid.
That’s not a premium problem. That’s a revenue problem.
+20%
A mod of 1.20 adds 20% to your workers’ comp premium. On a $50,000 policy that’s $10,000 extra. Every year.
OPEN
Open reserves on closed claims inflate your mod automatically. Carriers don’t close them. Nobody tells you. You just keep paying.
WRONG
Wrong class codes mean your expected losses are calculated on the wrong baseline. Your mod looks worse than it is — and you have no idea.
The Offer
Not a sales call. Not a quote. A real analysis of your mod — what’s in it, what’s driving it, and whether anything looks wrong.
We verify which claims are inside your rated experience period and which shouldn’t be there. Misplaced claims inflate your mod every year they sit in the calculation.
We identify claims still carrying reserves that should have closed. An open reserve keeps a claim’s full cost on your mod until somebody pushes the carrier to close it.
We cross-reference your payroll classifications against your actual scope of work. Wrong codes mean wrong expected losses — and a mod that doesn’t reflect your real risk profile.
We show you where your mod is headed at your next renewal based on your current claims activity — not just where it is today. That’s the number that matters for next year’s premium and bid eligibility.
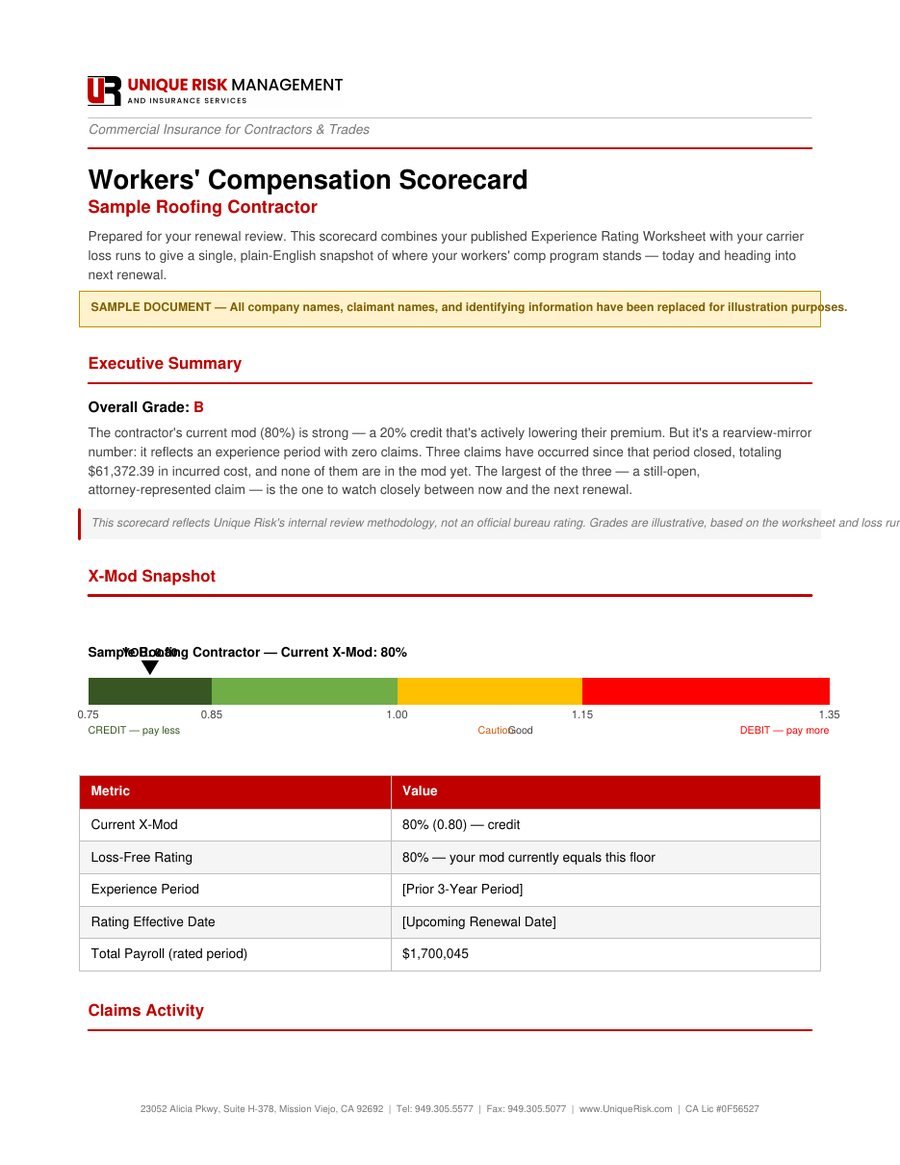
You receive a written scorecard — plain English, no jargon — showing exactly where your program stands and what, if anything, needs attention.
View the full sample (PDF)
Sample scorecard — de-identified for illustration. This is what you receive.
Real Result
A California contractor’s workers’ comp premium jumped from $4,270 to $21,751 at renewal. No phone call from their carrier. No site visit. No explanation. Just an automated notification and a bill that was $17,481 higher than the year before.
Here’s what their payroll provider’s algorithm did: it auto-reclassified half their staff into Class Code 3274 — a heavy processing and manufacturing rate — with no review of what those workers actually do on the job.
We were called at noon.
We audited their actual field operations, verified the governing classification directly against WCIRB rules, and proved Class Code 3274 was wrong. The correct code was 5128 — Instrument Installation.
Final corrected premium: $6,612.
$15,139 returned to the business owner. Same afternoon.
Most contractors never catch this. Their broker prices the renewal, the software assigns the code, and nobody looks at whether the code matches the work.
We look. Every time. For free.
Social Proof
“A general contractor had strict insurance requirements that were holding up work for us. Unique Risk stepped in and worked directly with the GC to ensure every requirement was met — so we could move forward and keep growing the business.”
“We used to lose time waiting on certificates of insurance — they’d take forever and were rarely right the first time, which held up getting paid. Unique Risk fixed that. Now certificates come back correct within 30 minutes, and we never have to ask twice.”
“I’ve been with them about 15 years. Michelle is fantastic — responsive, great communication, and she takes care of everything for us.”
Why Unique Risk
We don’t write homeowners, auto, or life. Every client we have is in the trades. We know your world before you explain it.
We don’t lead with price. We lead with your risk profile. If we can’t improve your program, we’ll tell you.
One team. One point of contact. They know your account, your claims, and your renewal date.
Nearly two decades writing contractor insurance in California. We’ve seen every version of what goes wrong — and how to fix it.
No obligation. We never contact your carrier, your broker, or the WCIRB on your behalf without your written authorization.
Process
Fill out the form below. One of our team members will reach out within 24 hours to walk you through what documents we need and answer any questions.
We need three things: 4–5 years of loss runs (requested directly from your carrier), your X-Mod worksheet (available from WCIRB at wcirb.com), and your current policy. We’ll help you track them down if you run into any trouble.
Within 3–5 business days of receiving your documents, we deliver your written WC Scorecard — a plain-English analysis of where your mod stands, what’s driving it, and what to watch before your next renewal.
That’s it. No commitment. No pressure to switch brokers. Just a straight read on your numbers from people who do this every day.
Request
Takes 60 seconds. We’ll handle the rest.
Your information is never sold or shared. We review every submission personally and respond within one business day.
Call us at 949.305.5577 or email service@uniquerisk.com
Serving CA contractors since 2007 · CA Lic #0F56527